You are finalizing next year’s hiring plan. The financial reports appear to support expansion, but finance is still chasing supplier invoices and explaining an old payroll balance. The books are closed. But leadership still has questions about the numbers. That distinction matters.
A completed month-end close tells you that the accounting process reached an endpoint. It does not necessarily mean every material balance is supported, every exception is resolved, or every number has been reviewed closely enough to support an important business decision. The real test is whether leadership can rely on the reports when making the next hiring, spending, financing, or operating decision.
Closed Books Do Not Always Mean Trusted Numbers
One warning sign our Controllers pay attention to is a close that appears complete on the surface but still raises important questions underneath. A balance may have been carried forward for months without a clear explanation. A report may have been issued and then changed later. An unusual adjustment may have been posted correctly without anyone asking why the same adjustment keeps appearing. None of these necessarily means the financial statements are wrong. But they can make leadership less confident in using them.
When we review a finance function, the issue is not always whether someone completed the accounting work. We want to know whether someone is accountable for challenging unusual balances, following unresolved items through to resolution, and deciding whether the results make sense. That is where a strong close becomes more than a deadline. It becomes a management tool.
Look Beyond Whether the Reconciliation “Agrees”
A reconciliation can technically agree and still leave a business with a problem. For example, a receivables ledger may match the accounting records while still containing an old disputed invoice that the company may never collect. The totals agree, but the balance still requires judgment.
When we review reconciliations, we look beyond whether the numbers tie to understand what is driving the balances, identify unusual items, and determine whether any important questions remain unresolved. We want to know what is sitting inside those numbers, what remains unresolved, and whether someone is actually paying attention to the exceptions. That matters particularly for cash, receivables, payables, payroll liabilities, taxes, and debt, where an unexplained balance can affect both reporting and decision-making.
Recurring adjustments deserve the same attention. If the same correction appears every monthposting the entry correctly may solve the immediate accounting problem without solving the underlying one. The cause could be a system configuration, unclear coding, missing information, or a process that was never designed properly in the first place. Correcting the entry should not replace correcting the process that caused it. That is one of the clearest differences between simply completing a close and actually improving the finance function.
A Number Is Only Useful If You Can Explain What Changed
Leadership does not make decisions from variances alone. They make decisions based on what those variances mean. Suppose payroll expense is higher than expectedThat could reflect new hires, overtime, bonuses, higher benefits costs, or an accounting classification issue. Those are very different business situations.
If the increase reflects additional employees who are already contributing to revenue, leadership may view the expense differently than if it comes from unexpected overtime or incorrect coding. The number on the report is the starting point. The explanation determines what management should do next. That is why we look for reporting that answers more than “what changed?” We want to know what changed, why it changed, whether the explanation is supported, and whether management needs to act.
The same principle applies when costs have not yet appeared in the accounts. A business can appear more profitable simply because completed work has not yet been invoiced. Before leadership makes a spending or hiring decision based on reported profit, finance should be confident that the results reflect what actually happened during the period. And when a report changes after leadership has already reviewed it, the change should be visible and explained. Quietly replacing the original version may make the file look cleaner, but it removes useful context about how the numbers evolved.
Approval Does Not End the Payment Risk
We also look beyond whether an invoice was properly approved. An owner may approve a legitimate supplier invoice, but that approval does not necessarily cover a later change to the supplier’s banking details. This is an important distinction because payment risk does not always correspond directly to the dollar value of a transaction. A routine payment to a long-standing vendor may be relatively predictable, while a smaller payment involving newly changed banking information may deserve significantly more scrutiny.
The independently verifying payment changes, including changes to account numbers or payment procedures, through a trusted contact channel. The practical lesson is straightforward: approval should protect the payment process, not just the invoice. Where possible, the person maintaining vendor information, preparing payments, and releasing funds should not have unrestricted control over all three steps. Smaller finance teams may not be able to create complete separation, but they can still introduce meaningful independent review.
The question we would ask is not simply, “Was this payment approved?” to release?”
Who Can Change the Numbers After They Have Been Reviewed?
Another question we ask is simple: after leadership has reviewed the numbers, who can still change them?
The issue is not whether someone has system access. It is whether that access still matches the responsibility they currently have. Particular attention should go to people who can change vendor banking information, post significant adjustments, or access administrator-level settings. Temporary access can also become permanent if nobody reviews it after the original need has passed.
The such as individual accounts, multifactor authentication, limiting functionality to what users need, and removing access when it is no longer required. Those safeguards matter, but they work best when the business also has clear ownership over the finance process. New software does not automatically create stronger controls. Technology can make a good process faster. It cannot decide who owns an exception, challenge an unusual result, or explain why the numbers changed.
Sometimes the Control Problem Is Really an Accountability Problem
Not every finance problem is caused by a lack of technical ability. In one finance engagement for a construction company, our team was brought in because leadership believed an accounting manager was underperforming. The concern had been building for months, and termination was being considered. After looking more closely, we found that the situation was more complicated. Expectations were unclear, communication gaps existed, and the manager had not received enough onboarding or structure to succeed.
The response was not simply to replace the person. Responsibilities were clarified, a task checklist was introduced, training was provided, and ongoing feedback was established. The accounting manager was retained. That experience reinforced something we see in finance functions: a documented process does not create accountability when nobody is clear about who owns the outcome.
The same principle applies to financial controls. A close checklist can tell people what should happen, but it cannot replace clear ownership, appropriate review, and escalation when something does not happen as expected. Before deciding that the business needs another person, it is worth asking whether the existing team has clear responsibilities, adequate support, and a defined standard for what “complete” actually means.
When Does Controller-Level Support Make Sense?
Not every control problem requires a Controller. When invoices are not being entered because the finance team lacks processing capacity, additional support may be more appropriate. If responsibilities are unclear, defining ownership may solve more than adding another person. For a business dealing with a specific year-end issue, a focused project may be enough.
A pattern we often see is that the accounting work is getting done, but nobody is consistently challenging the results. Significant balances, adjustments, and reporting issues may be processed without the level of review they require. That is where Controller-level oversight can become valuable.
Recurring close delays, unresolved exceptions, or uncertainty about who is responsible for challenging unusual results can indicate that the finance function needs more oversight rather than simply more processing capacity. The right question is not whether the company has reached a particular revenue level or transaction volume. It is whether the work requires a level of financial oversight that the current team cannot consistently provide.
Where Should You Start Before the Next Close?
You do not need to redesign every finance process before year-end. Start with three questions.
- Which unresolved numbers could change a business decision?
Focus on significant balances, recurring adjustments, and reporting changes that could affect hiring, spending, financing, or other important decisions.
- Who can approve or change high-risk transactions?
Pay particular attention to payment details, vendor changes, significant adjustments, and system access. Risk should be assessed based on what could go wrong, not only on the dollar amount involved.
- Who owns the exceptions?
An unresolved issue without an owner is not really being managed. Someone should be accountable for resolving it, escalating it, or explaining why it remains open.
For Canadian businesses, CRA recordkeeping requirements also reinforce the importance of maintaining reliable and complete records supported by appropriate documentation.
The goal is not a perfect close with zero adjustments. It is knowing which numbers matter, understanding what changed, and giving leadership enough confidence in the underlying information to make decisions.
Don’t Wait Until Year-End to Find Out What the Numbers Mean
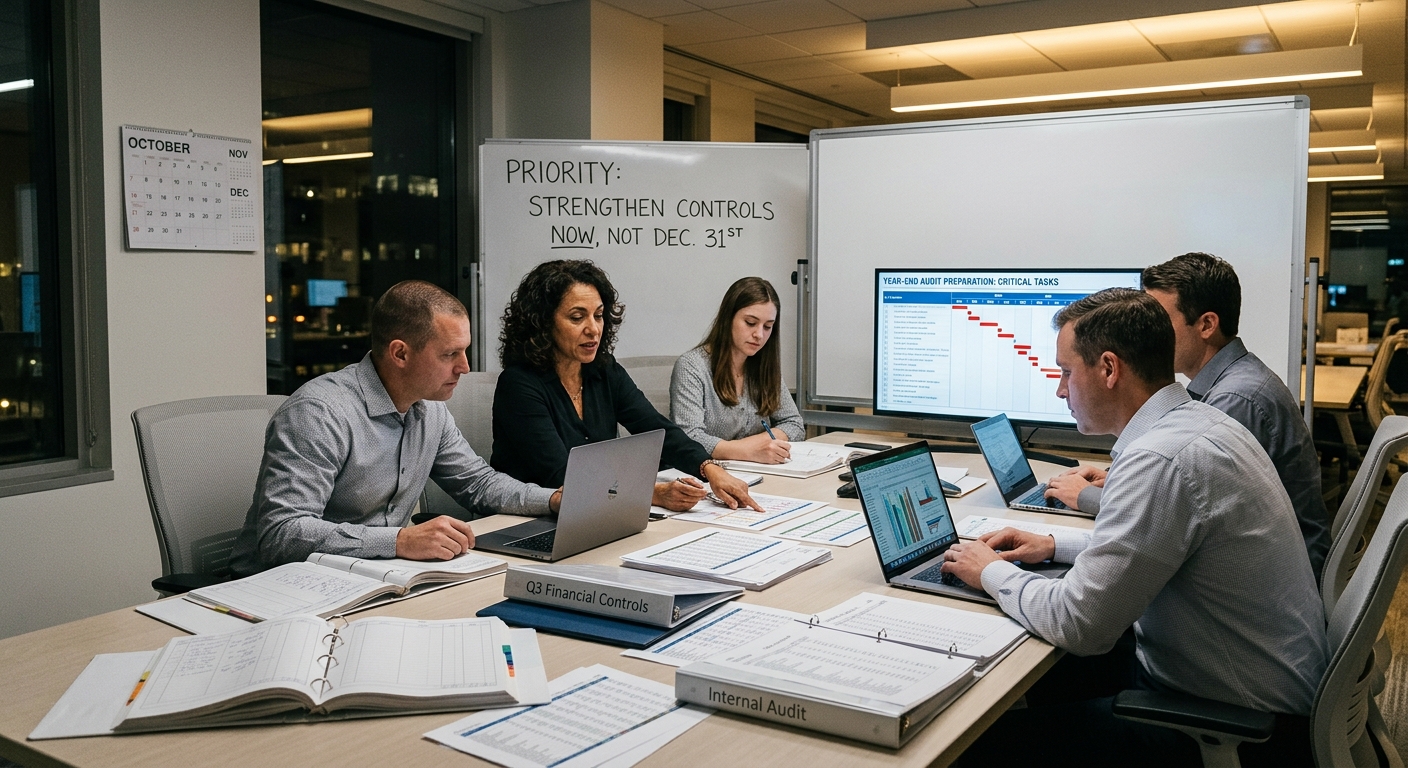
The real risk is not that a business has an adjustment at year-end. The risk is discovering too late that next year’s hiring plan, spending decisions, or financing assumptions were based on numbers the finance team could not confidently explain. A strong month-end close should give leadership more than a completed report. It should give them confidence in the information behind the report.
If your team is closing the books but leadership still has questions about whether the numbers can be relied on, talk with the Finance Group about where those gaps are showing up and what level of support makes sense.
Key Takeaways
- Closed books are not necessarily trusted books. Leadership needs confidence that significant balances are supported and exceptions are understood.
- Recurring corrections are worth investigating. The better question is often why the same issue keeps happening, not simply how to correct the entry.
- Controls should follow risk. Payment changes, significant adjustments, and access rights deserve attention because their impact can extend beyond the dollar value involved.
- The right finance support depends on the gap. Capacity, accountability, controls, and Controller oversight are different problems and require different solutions.
Dorothy Zubel CPA, CMA
Co-Founder, CEO
 Follow on Linkedin