Your accounting team is busy, but the work keeps piling up. Invoices are entered into multiple systems, month-end reports require hours of spreadsheet adjustments, and employees spend valuable time tracking down information that should already be available.
Before approving another hire, leadership needs to ask a different question: is the business dealing with more accounting work, or is the existing process creating unnecessary work?
As businesses grow, processes that once worked well can become increasingly difficult to manage. More transactions and reporting requirements create additional handoffs, but they don’t necessarily require more manual effort. When employees repeatedly enter, transfer, or correct the same information, the problem may be the workflow rather than the team’s capacity.
Why Growing Businesses Start Doing Accounting Work Twice
Duplicate work often begins with a reasonable workaround. An employee builds an invoice tracker because approvals are difficult to follow in email, or finance creates a spreadsheet because an existing report does not answer management’s questions. Over time, the workaround becomes another record to maintain alongside the accounting system.
Growth exposes the weakness in that arrangement. More customers, vendors, departments, and reporting needs create more handoffs, while employees continue using a process designed for a smaller business. The team may become busier without gaining a dependable way to see what has been completed, what is missing, and who should act next.
The warning sign is repeated effort without a distinct purpose. Entering an invoice into two systems deserves scrutiny, while a separate review of that invoice may protect the business. Leadership needs to distinguish avoidable duplication from the preparation, authorization, and independent review that support financial control.
Where Accounting Teams Lose the Most Time
Small inefficiencies matter most when they recur across a growing number of transactions. Accounts payable, customer invoicing, expenses, reconciliations, and monthly reporting deserve particular attention because repeated delays or corrections can consume more capacity as the business grows.
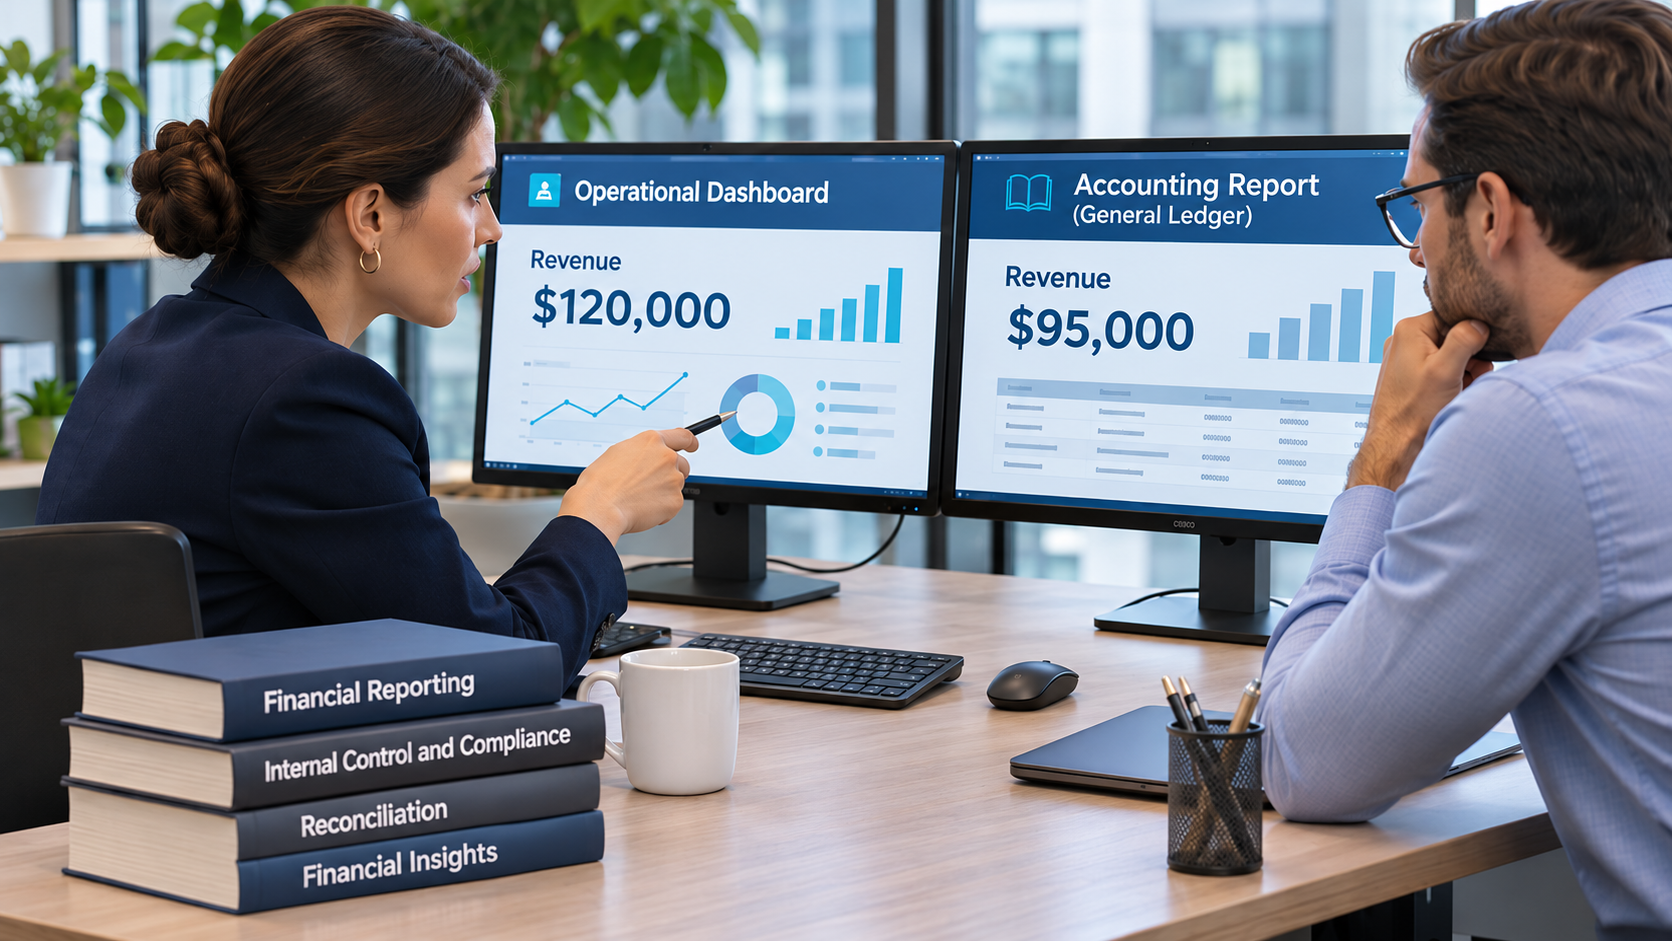
Consider a management report that should provide a straightforward view of financial performance. Instead, finance exports several files, changes account groupings, repairs formulas, investigates differences, and formats the results before analysis can begin. If the same corrections recur each month, the issue is unlikely to be the report itself. Something in the source information or reporting process needs attention.
These recurring problems are worth investigating:
|
Recurring symptom |
Question to investigate |
| Invoice details entered more than once | Which system should hold the original record? |
| Approvals repeatedly chased by email | Are routing, deadlines, and backup approvers clear? |
| Monthly reports rebuilt in spreadsheets | Which adjustments recur, and why are they needed? |
| Reconciliation differences repeatedly corrected | Is the cause timing, missing data, coding, or integration? |
| Work depends on one employee | Are procedures and exception decisions documented? |
The important distinction is whether employees are performing necessary accounting work or compensating for a process that does not function properly.
When assessing bookkeeping services, look beyond whether transactions are being processed accurately. Understand what employees must repeatedly do to produce those records and who is responsible for resolving problems when information is missing or incorrect.
Measure the Cost Before Choosing a Solution
A hiring decision is difficult to assess when leadership knows the team is busy but cannot explain where its time goes. A short time and task audit can make that workload visible. Two representative weeks, extended to capture a month-end close where necessary, provide a starting point for recording tasks, owners, frequency, time, systems, handoffs, and reasons for rework.
Processing time and waiting time reveal different problems. An invoice might take ten minutes to enter but spend several days awaiting approval. Measuring employee effort alone would miss the bottleneck.
Consider a hypothetical employee who spends ten hours a month rebuilding reports. At a fully loaded labor cost of $50 an hour, that represents 120 hours and $6,000 of annual labor capacity. Review time and recurring corrections would add to the estimate, while any separate costs should be supported by actual records.
Recovering those hours does not automatically reduce payroll expense. The benefit may be less overtime, an avoided hire, or more time for receivables follow-up and analysis. Identify the intended use of that capacity before presenting it as a financial return and avoid counting the same hours as both cash savings and redeployed work.
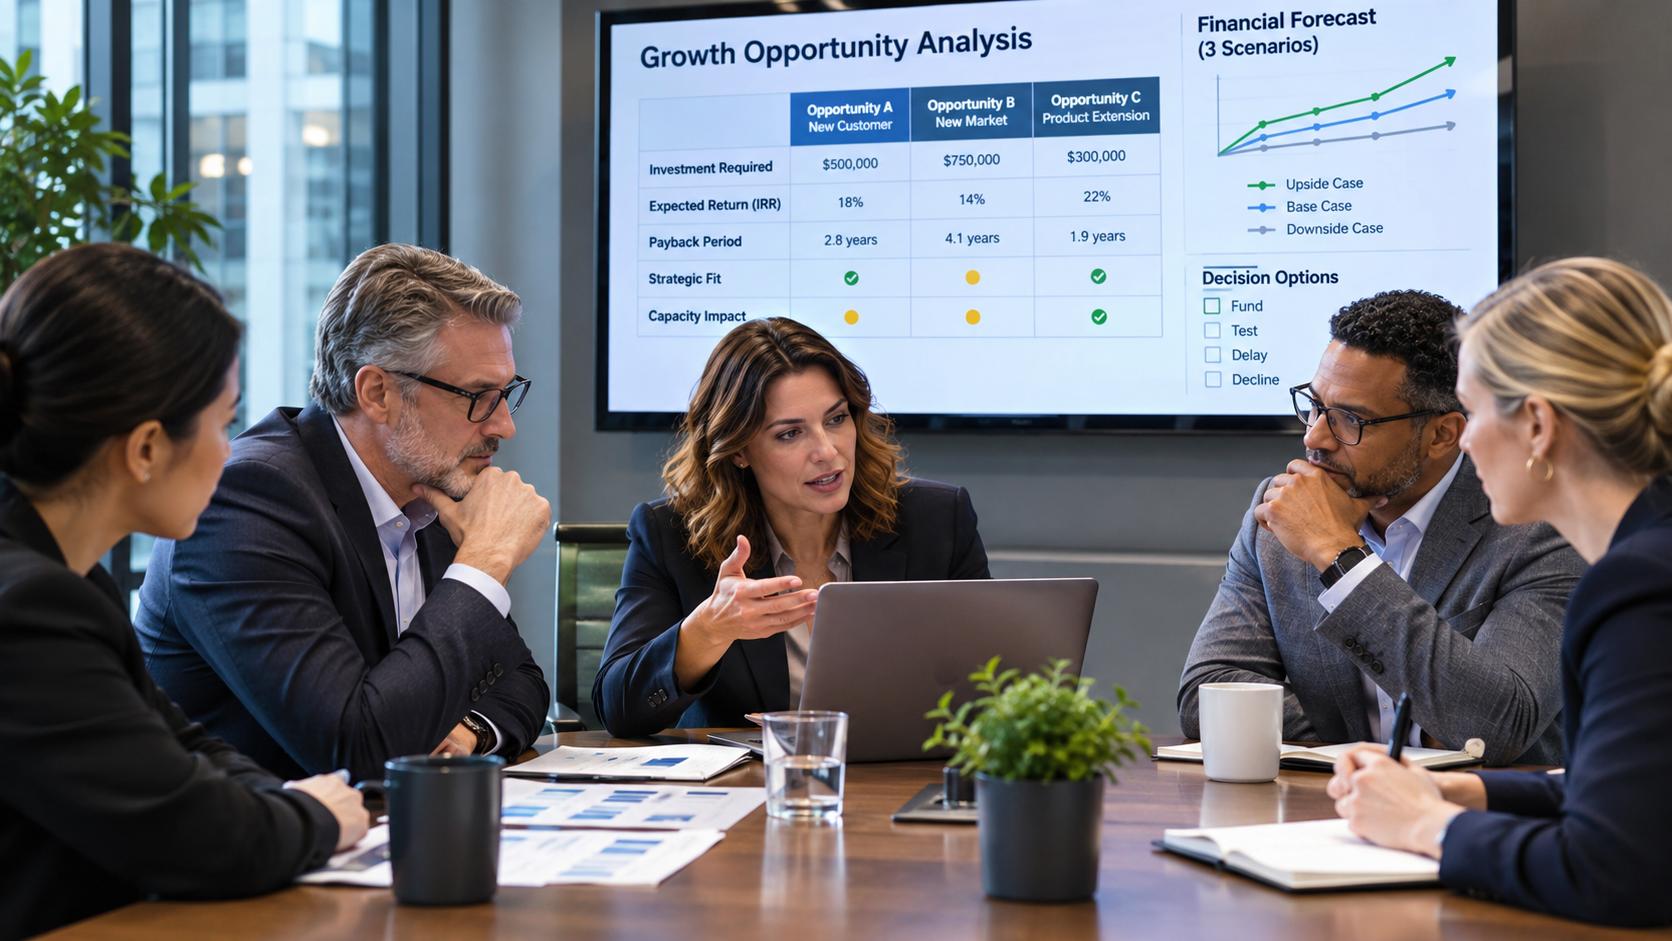
The strongest improvement opportunities combine substantial recurring effort with a feasible way to reduce delays or errors. Their expected benefit needs to justify setup costs, training, ongoing fees, and maintenance. Control requirements remain a separate consideration: a required authorization should not disappear simply because removing it would save time.
Simplify the Workflow Before Automating It
Automation is most useful when the business understands what should happen and which exceptions need attention. AICPA & CIMA’s guidance for accounting firms recommends identifying repetitive bottlenecks and assessing whether underlying processes are clear and well defined. That is a useful starting point for an internal finance team too.
A workflow map should explain why each step exists, from the original transaction through to reporting. Some steps create information, others authorize or review it, and some merely move it between records. That distinction helps identify unnecessary transfers without removing the ownership and reviews the business needs.
Existing software may already support part of the solution. Sage Intacct, for example, offers matching rules that connect incoming bank transactions with existing accounting transactions. These features can reduce manual matching for predictable transactions, but they do not establish that every match is appropriate or replace responsibility for reviewing exceptions.
A better process uses automation for routine transactions while directing unmatched or unusual items to an assigned reviewer. The underlying records and review trail still matter, even when fewer transactions require manual attention.
Technology can make a good process more efficient, but it will not resolve unclear responsibilities or inconsistent source information on its own.
When Bookkeeping Services or Different Support Make Sense
The right response depends on what is constraining the team. A processing backlog, an ownership gap, and a platform limitation can create similar symptoms while requiring different interventions.
|
Underlying problem |
Response to consider |
| Unnecessary transfers or unused reports | Simplify or eliminate the work |
| Different methods for the same task | Standardize procedures and responsibilities |
| Predictable manual processing | Use suitable automation or integration |
| Insufficient routine processing capacity | Consider outsourced bookkeeping |
| Weak ownership of close, controls, or reporting | Consider fractional Controller oversight |
| Platform cannot reasonably meet requirements | Assess a system migration |
Outsourced bookkeeping can add routine processing capacity, but the scope must define responsibilities, required inputs, deadlines, and escalation. Changing providers will not resolve missing approvals or inconsistent source information unless someone also addresses those dependencies. When comparing bookkeeping services, ask who owns the handoffs between the provider and the internal team.
A fractional Controller addresses oversight needs such as close procedures, reporting quality, accounting policies, and controls. This support may be appropriate when bookkeepers can process transactions but recurring issues remain unresolved because nobody owns the overall process. The distinction is whether the business needs more execution capacity, stronger oversight, or both.
A system migration deserves consideration when the current platform cannot reasonably support reporting, integrations, controls, or operational complexity. Before committing to accounting system implementation, document those requirements and assess whether configuration or integration could meet them. Include data cleanup, testing, training, and transition capacity in the decision rather than comparing subscription prices alone.
Measure Improvement Without Weakening Financial Control
A faster process is useful only if the information it produces remains dependable. Comparing similar reporting periods before and after a change can show whether processing hours, approval waiting time, reconciliation exceptions, recurring corrections, or days to close have improved.
Those measures should sit alongside evidence that transactions remain complete, accurate, supported, and appropriately authorized.
Deloitte’s guidance on financial close emphasizes standardized data and documented processes with clear owners, timelines, and controls. These foundations help ensure that improvements in efficiency do not compromise the reliability of financial information.
For example, if reporting time falls but reconciliation corrections increase, the process has not necessarily improved. The real benefit comes when finance can produce dependable information with less unnecessary effort, giving the team more capacity to support the business.
Stop Paying for Avoidable Repetition
An overloaded accounting team needs a clear understanding of the problem before leadership commits to more capacity. Better bookkeeping services can help when the scope addresses the actual constraint, but the first decision is which work the business needs, which work protects it, and which work exists only because the process has not kept pace. Removing that last category gives the team more room to deliver reliable information and support better business decisions.
If recurring rework is driving your next hiring or software decision, speak with the Finance Group about where your accounting processes may be creating unnecessary work. A clearer understanding of the underlying issues can help you decide where additional investment will make a difference.
Dorothy Zubel CPA, CMA
Co-Founder, CEO
 Follow on Linkedin