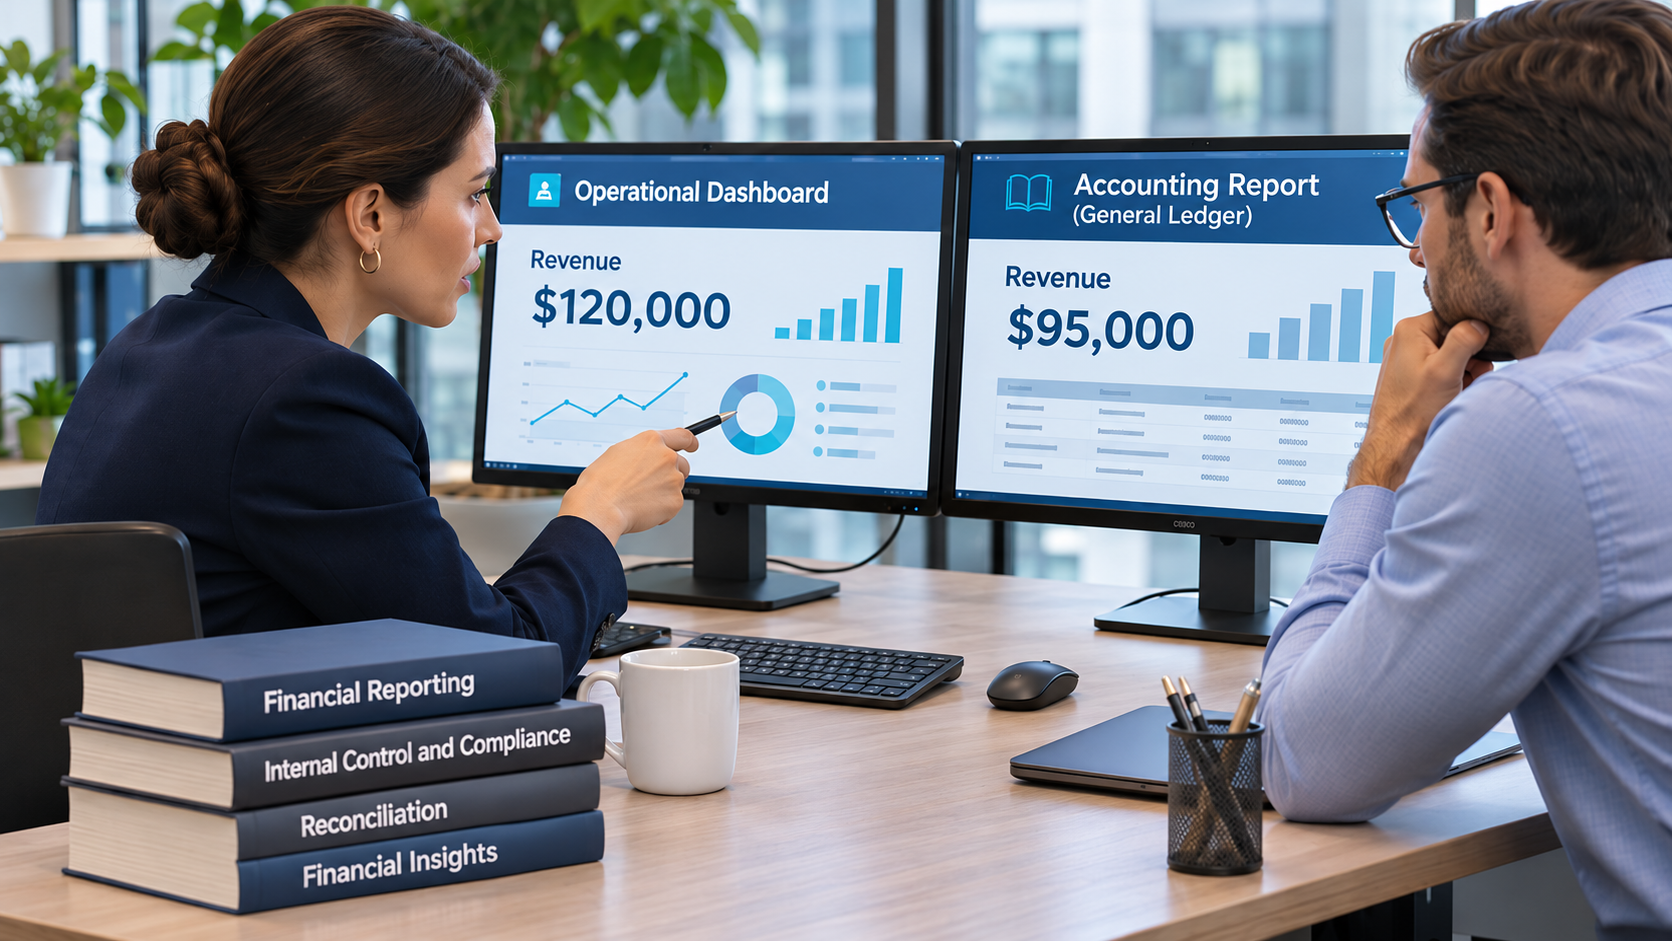
Imagine you’re preparing for a leadership meeting. The sales dashboard shows $120,000 in revenue for the month, but the accounting system reports only $95,000. The sales team sees a strong result, and leadership is considering another hire to support continued growth. Finance, however, is questioning why the numbers don’t match.
Before approving the additional position, leadership needs to understand which figure reflects the business’s actual financial performance. Is the difference related to signed contracts that have not yet been recognized as revenue? Are invoices missing from the accounting system? Or is information being recorded differently across departments?
These questions matter because the decision to hire involves more than whether sales are increasing. It requires an understanding of what the business has earned, what it has collected, and whether its financial position can support another ongoing commitment.
When two reports tell different stories, the instinct is often to find the incorrect number and fix it. But sometimes, neither report is wrong. The underlying problem is that different teams are working with different definitions, reporting periods, or sources of information without a clear understanding of how they connect.
As businesses grow, these differences become harder to manage informally. More departments, systems, and people contribute to financial information, making it increasingly important to understand how those numbers connect before using them to make business decisions.
Two Reports Can Be Correct and Still Tell Different Stories
A reporting discrepancy does not automatically mean someone has made an accounting error. Before deciding which report to trust, leadership needs to understand what each figure represents and whether the reports are actually measuring the same thing.
Revenue is a common example. A sales dashboard might show the value of contracts signed during the month, while the billing system records invoices issued and the accounting system recognizes revenue based on the applicable accounting requirements. Cash received from customers is another figure entirely. All four measurements are connected to business performance, but they do not necessarily represent the same financial activity.
The distinction becomes important when leadership uses one figure to make a decision that requires another.
Signed contracts can indicate future demand, but they do not automatically establish how much revenue has been earned or how much cash is available to support additional spending. For businesses reporting under IFRS, IFRS 15 guidance explains how revenue recognition reflects the transfer of promised goods or services to customers. Other businesses may follow different applicable accounting standards, so the accounting treatment needs to reflect the company’s reporting framework and circumstances.
The same issue can appear in operational reporting. A department might report strong project performance because its dashboard excludes certain costs, while finance includes those expenses in the company’s financial statements. The operational report may still be useful for measuring departmental activity, but it may not provide the complete financial picture leadership needs when assessing profitability.
This is why the question should not simply be which report is correct. Leadership needs to understand what each report is designed to measure, which decisions it can support, and whether the underlying information has been checked against the appropriate financial records. Once that is established, finance can determine whether the difference is legitimate or whether something needs to be corrected.
The Real Problem Is Often What Happens Behind the Numbers
When two reports are expected to agree but do not, correcting the difference may solve the immediate problem without addressing its cause. If the same discrepancy keeps appearing during every reporting cycle, the business is not dealing with an isolated accounting error. Something in the process is allowing incorrect or inconsistent information to enter the reporting system.
Consider a transaction that repeatedly appears in the wrong account. Finance identifies the issue during month-end close, posts an adjustment, and produces the corrected financial statements. The reports now agree, but the original transaction is still being coded incorrectly. Unless someone investigates why the error occurred and how it escaped review, the same adjustment will likely be needed again next month.
Correcting the number should not replace correcting the process that caused it to be wrong.
The same thinking applies to discrepancies between operational systems and accounting records. An integration might import duplicate transactions, a manual spreadsheet might contain outdated information, or a department might apply a different reporting cutoff. Replacing the accounting software may appear to be the obvious solution, but new technology will not automatically resolve inconsistent processes or unclear responsibilities.
A more useful approach is to trace the difference back to its source. If a management dashboard reports $500,000 while the general ledger shows $487,000, finance should be able to explain the $13,000 variance through supporting transactions, timing differences, or documented adjustments. The objective is not to force the totals to match. It is to understand what happened and determine whether the difference reflects a legitimate reporting distinction or an underlying error.
Supporting records are important here, too.
The IRS guidance on business recordkeeping and the Canada Revenue Agency’s business records requirements both emphasize the importance of maintaining documentation that supports business transactions and reported amounts. Requirements differ between jurisdictions, but the principle is relevant to any organization: financial figures should be traceable to reliable supporting information.
We saw a similar challenge in a professional services business following an acquisition. Management struggled to obtain a consistent view of financial performance across both businesses, making it difficult to effectively plan resources and make informed strategic decisions. tFG addressed this by strengthening financial reporting processes and improving forecasting to provide management with a clearer and more consolidated picture of the organization’s financial position. This gave management better visibility into business performance, supporting more informed resource planning, financial oversight, and strategic decision-making.
A similar issue arose in a cabinetry and millwork business, where management lacked a consistent way to measure performance across Factory, Sales, Design and Estimating, HR, and Operations. The engagement involved developing department-specific Power BI dashboards and establishing a reporting framework that gave management a clearer view of performance across the business.
Both engagements highlight something we consider important: presenting information differently does not automatically make it more useful. Leadership needs to understand what the numbers represent, how they connect to business activity, and whether they provide enough context to support decisions.
Better Reporting Requires Clear Ownership, Not Just Better Software
Financial information often passes through several departments before it appears in a management report. Sales records customer activity, operations tracks project performance, payroll processes employee costs, and finance consolidates the information into financial statements. When responsibilities are unclear, errors can pass between systems without anyone recognizing that something needs to be reviewed.
Finance should not be expected to guarantee the accuracy of every operational figure if the information entering the accounting system has not been properly maintained. At the same time, department leaders cannot assume finance will identify every issue after the fact. Each team needs to understand its responsibility for the information it produces and how that information affects the wider business.
We saw how important this can be in one construction company engagement. Leadership was considering replacing an Accounting Manager because of concerns about their performance. However, the assessment found that expectations had not been clearly communicated, onboarding and training were insufficient. Once these issues were addressed, the Accounting Manager was retained. This demonstrated how addressing unclear responsibilities and gaps in management support can resolve what initially appears to be an individual performance problem.
The same principle applies when different departments maintain competing versions of financial information.
Sales should understand what its reported contract values represent, while finance should establish how those figures connect to recognized revenue and the accounting records. Leadership, in turn, needs to know which measure is appropriate when assessing performance or approving an investment.
The U.S. Government Accountability Office’s Green Book provides an authoritative reference on management responsibility, information quality, accountability, and internal controls. It is designed for federal agencies rather than private businesses, so it should not be treated as a universal compliance requirement. However, its principles help illustrate why reliable reporting depends on more than the software or accounting team responsible for producing it.
For US public companies, the PCAOB’s AS 2201 standard addresses the audit of internal control over financial reporting alongside financial statement audits. The SEC’s management guidance on internal controls also emphasizes a risk-based approach to assessing controls. These requirements apply in specific public-company contexts, but they reinforce an important broader business consideration: controls should be designed around the risks that could affect the reliability of financial information.
Technology can certainly improve reporting. Integrated accounting platforms, ERP systems, and automated dashboards can reduce manual work and make information more accessible. However, systems still need appropriate configuration, consistent data definitions, and people who understand how information should move between departments.
An accounting system implementation also needs to account for how information moves through the business. Chart of accounts design, data migration, system configuration, and integrations all affect the quality of the information management eventually receives. Installing new software without addressing the underlying processes can simply carry existing problems into a different system. These considerations are also reflected in the Finance Group’s accounting system implementation work.
Reliable Reporting Should Explain What Changed, Not Just Show the Numbers
A financial report becomes useful when it helps leadership understand what is happening in the business. Showing that a number has increased or decreased is only the starting point. Finance needs to explain what drove the movement and whether it represents a genuine business change or a reporting issue.
Consider payroll expense increasing significantly compared with the previous month. The initial report tells leadership that costs have increased, but it does not explain whether the difference comes from new employees, overtime, bonuses, benefits, or an incorrect allocation. Those possibilities have different implications for staffing decisions and future budgets. Without that context, leadership could respond to the wrong problem.
The same applies to revenue growth, operating expenses, project profitability, and cash flow. A higher revenue figure does not automatically mean the business is more profitable, just as a positive cash balance does not necessarily mean every dollar is available to spend. Finance needs to connect the reported results with the underlying activity before presenting them as a basis for management decisions.
For finance teams, this means being willing to question unusual movements rather than simply presenting the figures and assuming leadership will interpret them correctly. When payroll has increased, explain why. If revenue differs between the sales dashboard and accounting records, identify what each figure includes. For recurring adjustments that appear during the close, investigate whether the underlying process needs attention.
The level of review should also reflect the significance of the decision.
A minor timing difference in an operational dashboard may not require the same investigation as an unexplained balance that could materially affect financial statements, financing discussions, or a major investment decision. What matters is that important differences are documented, understood, and resolved appropriately rather than quietly carried forward.
When Does a Business Need Financial Controller Support?
As a business grows, financial reporting usually becomes more complicated. More employees, customers, departments, locations, systems, and transactions create additional opportunities for information to become inconsistent. The accounting team may still be able to process transactions and complete the monthly close, but that does not necessarily mean the business has enough oversight to identify reporting weaknesses and challenge the numbers before leadership relies on them.
There comes a point when completing the monthly close is no longer enough. Leadership also needs someone who can question unusual balances, challenge reporting assumptions, and make sure recurring issues are being addressed rather than corrected temporarily. That level of oversight becomes particularly important when management is relying on financial information to make decisions about hiring, investment, financing, or growth.
Not every reporting discrepancy requires a new Controller or a complete finance transformation. Sometimes the issue is a bookkeeping backlog, an integration that needs attention, or a specific reporting responsibility that has not been clearly assigned. The important thing is to understand whether the problem is isolated or whether it reflects a wider gap in financial oversight.
The level of support needed depends on where the problem sits.
If transaction processing, reconciliations, or month-end preparation are falling behind, the issue may be accounting capacity rather than financial oversight. Consistent bookkeeping and account reconciliations provide the foundation for reliable financial reporting.
If the underlying figures are available but nobody is reviewing unusual balances, challenging reporting assumptions, or taking responsibility for financial controls, the gap is different. That may call for additional Controller-level oversight, particularly around the month-end close, financial statements, reconciliations, reporting, and accounting processes.
Where reporting issues also affect broader planning, forecasting, or investment decisions, fractional CFO support may provide an additional level of strategic financial guidance. The appropriate level of involvement depends on the complexity of the business and the financial responsibilities that need attention, rather than assuming every reporting problem requires the same solution.
The goal is not to introduce another layer of management or another reporting tool simply because two systems disagree. It is to establish whether the business has the right processes, accountability, and financial oversight to produce information that leadership can confidently use.
Financial Decisions Need Numbers That Tell the Full Story
When two reports tell different stories, leadership needs to understand what each figure represents, where the information originated, and whether the difference reflects a legitimate reporting distinction or an underlying problem. Left unexplained, these discrepancies can become part of the normal reporting process, leaving leadership questioning the numbers instead of using them to make informed decisions.
A business should not have to wait until a major hiring decision, financing discussion, or year-end review to discover that its departments have been working with different versions of the numbers. If leadership is regularly questioning the figures presented to them, it is worth understanding where those differences originate before they become part of the normal reporting process. Sometimes the answer is a straightforward correction. Other times, it points to a wider issue with how information is recorded, reviewed, or communicated across the business. Understanding that distinction is what allows leadership to address the right problem.
Are you confident that the financial information guiding your business decisions tells the full story? If reporting inconsistencies, unclear financial processes, or limited visibility are making it difficult to move forward with confidence, connect with the Finance Group for a free consultation. Discuss your finance and accounting challenges with our team, identify where greater oversight is needed, and explore the right support for your business.
Dorothy Zubel CPA, CMA
Co-Founder, CEO
 Follow on Linkedin